Scrape Dallas Hotel Chain Location Data 2026
Author : Travel scrape | Published On : 23 Oct 2026
Introduction
Dallas has emerged as the leading U.S. hotel development market in 2026, with 183 hotel projects and 22,840 rooms in the construction pipeline at the end of Q2 2026. Lodging Econometrics reported that Dallas remained ahead of Atlanta, Nashville, Austin, and Phoenix, making the market particularly important for hotel developers, investors, franchise operators, real-estate analysts, and hospitality technology companies.
Scrape Dallas Hotel Chain Location Data 2026 to understanding where hotel brands are expanding, which locations are entering the pipeline, how many rooms are being added, and where competitive concentration is increasing. The dataset can combine operating properties with planned, under-construction, and proposed hotels to create a more complete view of Dallas' evolving accommodation landscape.
Hotel Chains Data Scraping can capture hotel names, brands, addresses, geographic coordinates, room counts, property categories, development status, opening timelines, and surrounding market attributes. Such structured information allows businesses to move beyond individual property research and evaluate the entire Dallas hotel ecosystem at scale.
Dallas hotel chain market intelligence becomes especially valuable because the market's development activity is distributed across Dallas and surrounding growth corridors. The Dallas market definition used in industry reporting includes Dallas and suburbs such as Plano and Frisco, while Fort Worth and Arlington are treated separately.
Dallas Hotel Development Market in 2026
Dallas entered 2026 with an even larger pipeline. At the end of Q1, the market had 184 projects representing 22,861 rooms, including 37 projects under construction, 68 scheduled to begin within 12 months, and 79 in early planning. By Q2, the pipeline stood at 183 projects and 22,840 rooms.
This slight quarterly change should not be interpreted as a collapse in development. Instead, it reflects the movement of projects through the development cycle, openings, cancellations, and new project additions. Dallas still held the largest pipeline among major U.S. markets in Q2.
| U.S. Hotel Market | Q2 2026 Pipeline Projects | Pipeline Rooms | Under Construction Projects | Under Construction Rooms | SN12 Projects | SN12 Rooms | Early Planning Projects |
|---|---|---|---|---|---|---|---|
| Dallas | 183 | 22,840 | 38 | 4,184 | 68 | 7,885 | 77 |
| Atlanta | 157 | 17,423 | 31 | 3,800+ | 61 | 6,761 | 74 |
| Nashville | 122 | 16,281 | 25+ | 3,000+ | 49 | 6,623 | 60+ |
| Austin | 116 | 13,875 | 25+ | 3,000+ | 59 | 6,542 | 50+ |
| Phoenix | 115 | 16,136 | 31 | 4,621 | 40+ | 5,000+ | 50+ |
| Indianapolis | 76 | 8,557 | 15+ | 2,000+ | 30+ | 3,000+ | 30+ |
| Tampa | 61 | 8,370 | 10+ | 1,500+ | 20+ | 2,500+ | 20+ |
| St. Louis | 59 | 6,373 | 10+ | 1,000+ | 20+ | 2,000+ | 20+ |
| Oahu Island | 11 | 2,850 | 5+ | 1,000+ | 3+ | 700+ | 3+ |
Dallas Q2 figures are reported by Lodging Econometrics; selected secondary-market stage figures are rounded/indicative where the cited Q2 reporting does not provide an exact breakdown.
The scale is significant. Dallas had 38 projects under construction totaling 4,184 rooms, the highest project count among U.S. markets in Q2. This creates an immediate need for location-level intelligence because the pipeline is not simply about the number of properties—it represents future room supply entering specific submarkets.
Why Dallas Hotel Chain Location Data Matters?
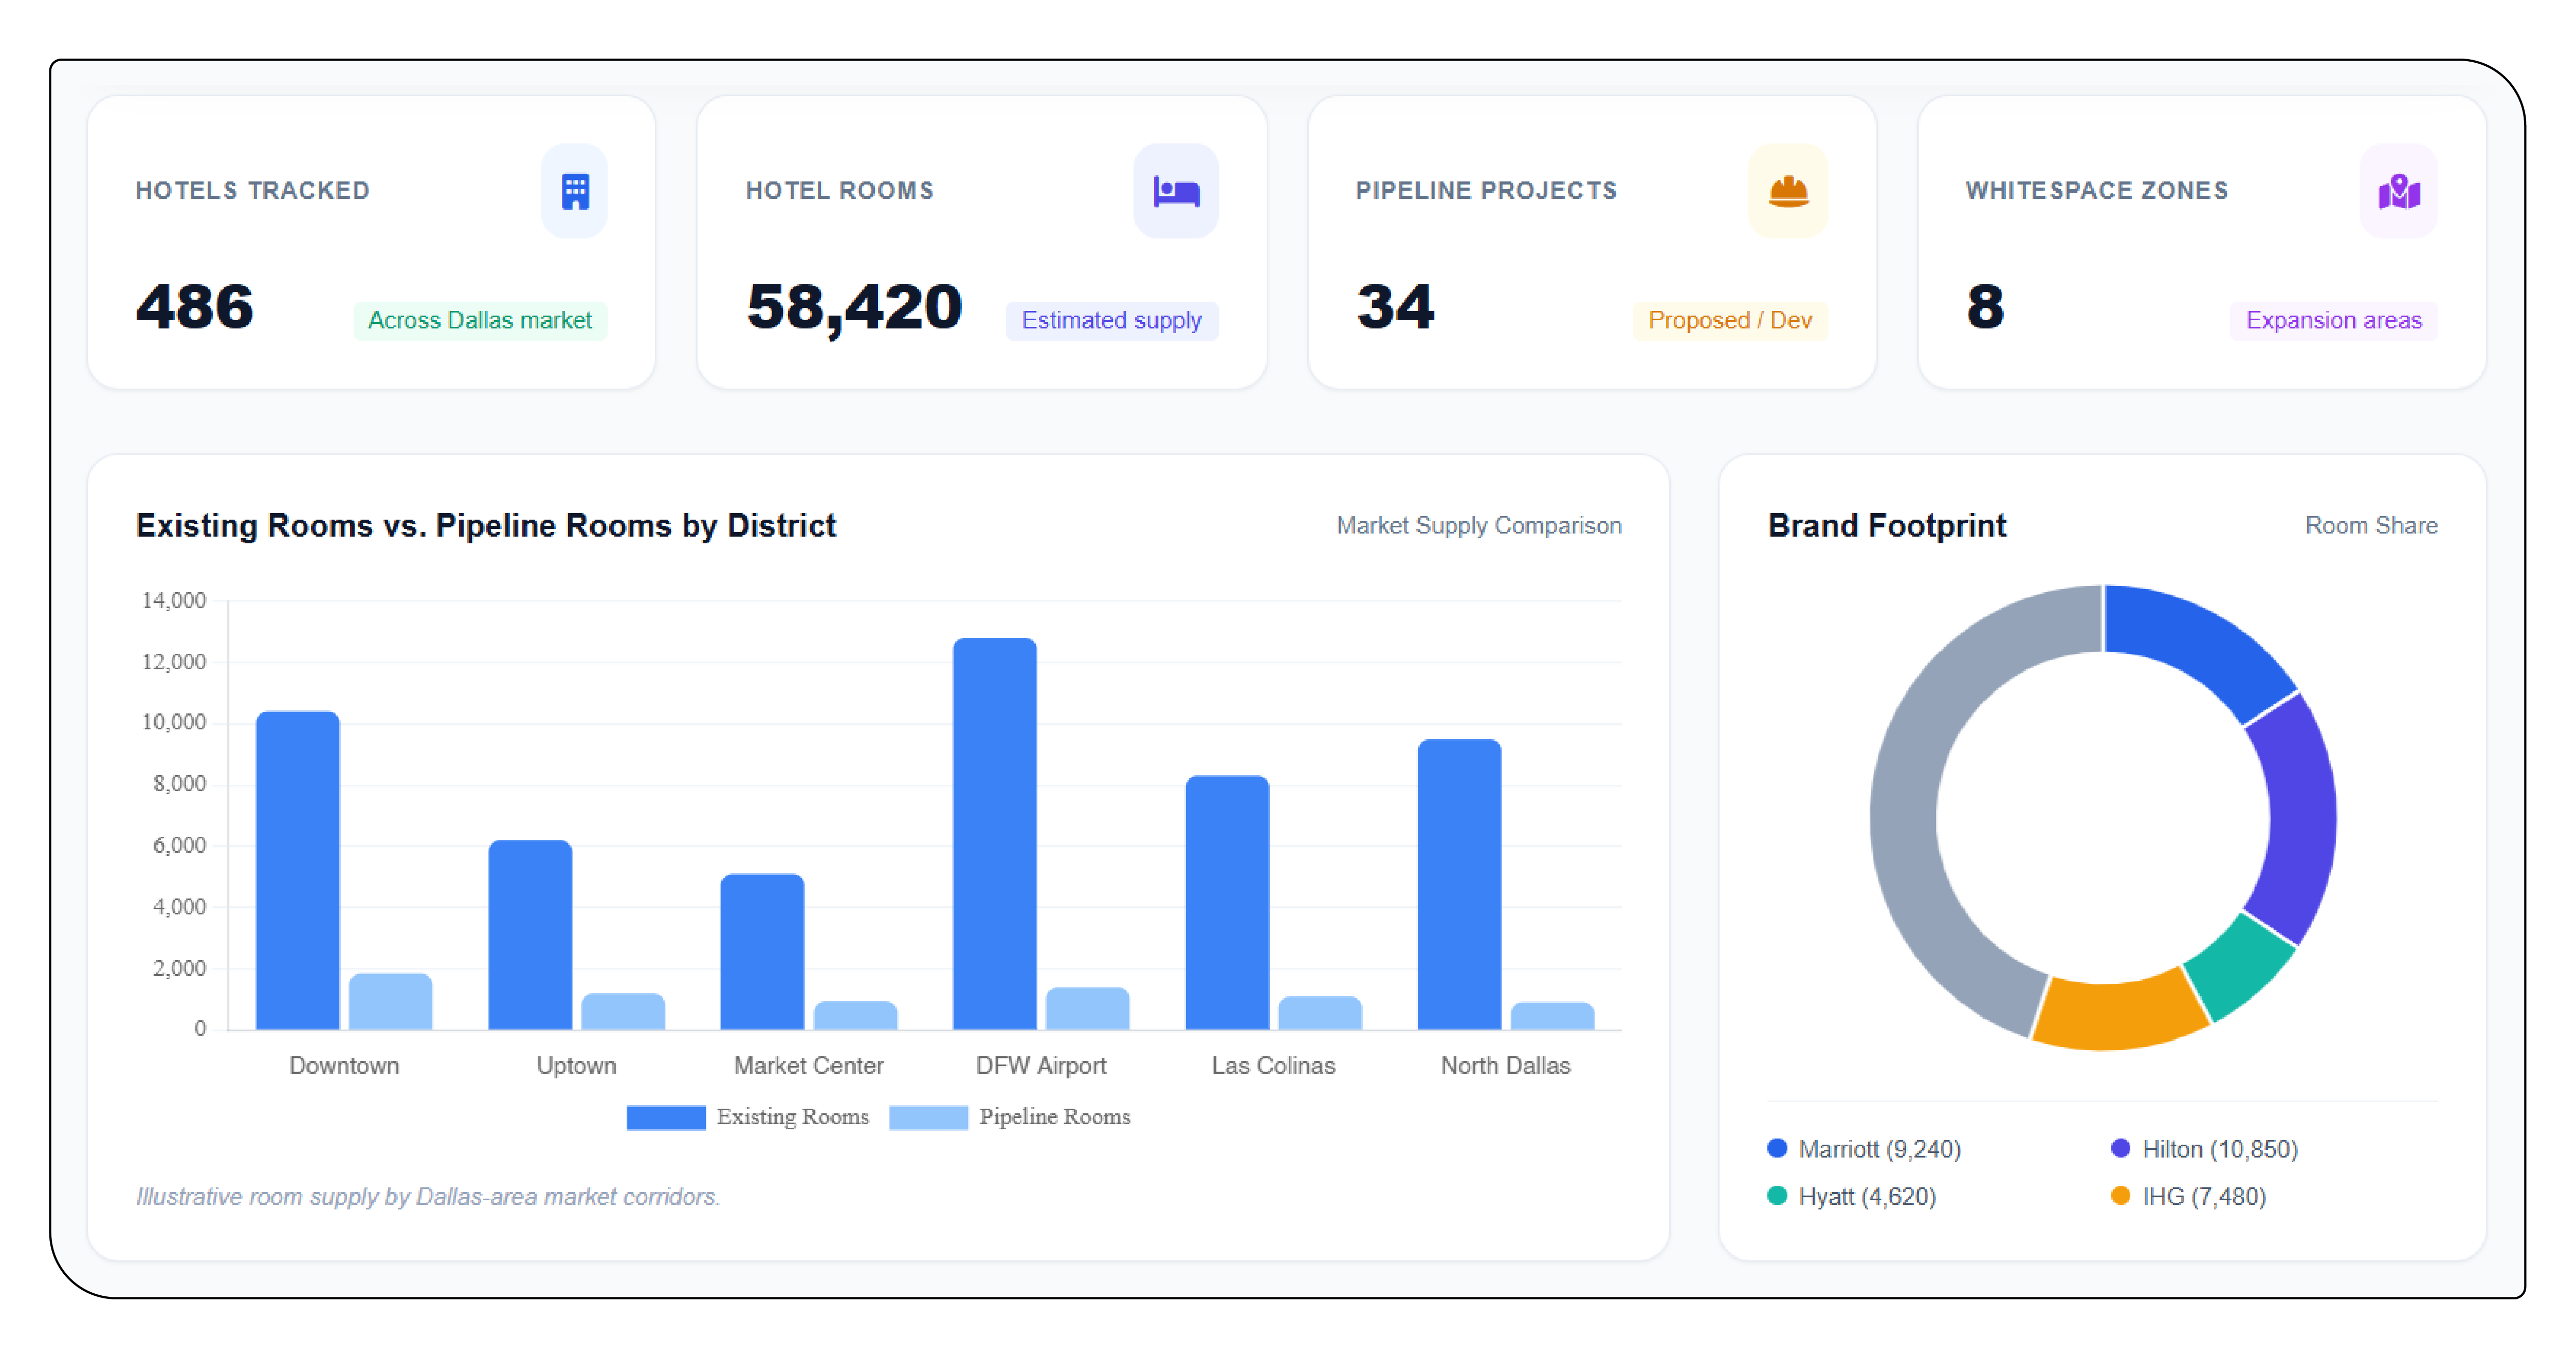
A hotel development pipeline becomes commercially useful when individual projects can be connected to precise locations and competitive environments. Location data can reveal whether a new Marriott, Hilton, Hyatt, IHG, or independent property is entering a high-demand business district, airport corridor, suburban growth zone, entertainment destination, or already saturated hotel cluster.
Hotel Chain Location Intelligence transforms raw property records into geographic market intelligence by connecting hotels with neighborhoods, business districts, transportation infrastructure, attractions, airports, convention facilities, restaurants, retail centers, and competing accommodation properties.
For investors, this helps answer critical questions: Is a proposed hotel entering an underserved area? Are multiple brands targeting the same customer segment? Is room supply expanding faster than demand? Which corridors are attracting premium brands?
For hotel chains, the same information can support territory planning and franchise expansion. Operators can compare their existing footprint with competitor locations and identify whitespace where brand presence remains limited.
Dallas Hotel Chain Location Mapping
Dallas hotel chain location mapping makes it possible to visualize operating and future hotel supply across the metropolitan market. A structured dataset can classify properties according to geographic coordinates, ZIP codes, neighborhoods, submarkets, development status, brand family, chain scale, room count, and expected opening year.
The result is a dynamic market map rather than a static hotel directory.
For example, a developer could filter for upper-midscale hotels planned within a defined radius of a major employment center. An investor could isolate luxury properties within a selected ZIP code. A hotel brand could identify locations where competitors have multiple properties but its own portfolio has limited penetration.
Location mapping also makes pipeline monitoring easier. Projects can be grouped into categories such as operating, under construction, planned start, early planning, announced, delayed, or cancelled.
Dallas Hotel Chain Competitive Location Analysis
Dallas hotel chain competitive location analysis can compare brands by property density, room supply, geographic coverage, chain scale, and development pipeline.
This matters because Dallas' development market is not homogeneous. A hotel project positioned in Plano faces a different competitive environment from one near downtown Dallas, the Dallas North Tollway, an airport corridor, or a major suburban employment center.
The following dataset structure illustrates how a hotel location intelligence program can organize individual properties and future projects.
| Property / Project | Brand Family | Chain Scale | Location / Submarket | Status 2026 | Rooms | Project Type | Expected Opening | Latitude | Longitude | Competitive Signal |
|---|---|---|---|---|---|---|---|---|---|---|
| Downtown Hotel Project | Marriott | Upscale | Downtown Dallas | Under Construction | 200 | New Build | 2027 | 32.7767 | -96.7970 | High business demand |
| Airport Corridor Project | Hilton | Upper Midscale | DFW Corridor | Planned | 150 | New Build | 2027 | 32.8998 | -97.0403 | Airport demand |
| Plano Business Hotel | Hyatt | Upscale | Plano | Early Planning | 180 | New Build | 2028 | 33.0198 | -96.6989 | Corporate demand |
| Frisco Lifestyle Hotel | Marriott | Upscale | Frisco | Planned | 190 | New Build | 2027 | 33.1507 | -96.8236 | Mixed-use growth |
| North Dallas Hotel | Hilton | Upper Midscale | North Dallas | Under Construction | 140 | New Build | 2026 | 32.9998 | -96.8010 | Competitive expansion |
| Tollway Hotel Project | IHG | Upscale | Dallas North Tollway | Early Planning | 175 | New Build | 2028 | 32.9500 | -96.8200 | Corridor opportunity |
| Convention District Hotel | Hyatt | Upper Upscale | Downtown Dallas | Planned | 250 | New Build | 2028 | 32.7758 | -96.7960 | Group travel |
| Frisco Mixed-Use Hotel | Independent | Upscale | Frisco | Planned | 190 | Mixed-Use | 2027 | 33.1500 | -96.8300 | Lifestyle demand |
| Galleria Area Hotel | Marriott | Upper Midscale | Galleria | Early Planning | 160 | New Build | 2028 | 32.9300 | -96.8000 | Retail tourism |
| Plano Corporate Hotel | Hilton | Upper Midscale | Legacy Corridor | Under Construction | 155 | New Build | 2027 | 33.0780 | -96.7960 | Office demand |
| Uptown Dallas Hotel | Hyatt | Luxury | Uptown | Proposed | 220 | New Build | 2029 | 32.8000 | -96.8000 | Premium segment |
| Southern Dallas Hotel | IHG | Midscale | South Dallas | Early Planning | 130 | New Build | 2028 | 32.7000 | -96.7800 | Emerging supply |
| Medical District Hotel | Marriott | Upscale | Medical District | Planned | 175 | New Build | 2028 | 32.8140 | -96.8400 | Healthcare demand |
| Las Colinas Hotel | Hilton | Upscale | Irving | Under Construction | 200 | New Build | 2027 | 32.8830 | -96.9700 | Corporate demand |
| Frisco Resort Project | Independent | Upper Upscale | Frisco | Proposed | 300 | Mixed-Use | 2029 | 33.1600 | -96.8400 | Leisure opportunity |
Illustrative location-intelligence schema for demonstrating the fields a Dallas hotel dataset can contain; these rows are not presented as verified individual project records.
Custom Scraping Pipelines
Custom Scraping Pipelines can continuously collect hotel location and development information from multiple publicly available sources and standardize it into an analytical database.
A pipeline can capture property name, parent company, brand, address, latitude and longitude, room inventory, amenities, opening date, construction stage, developer, project status, website information, and surrounding competitive properties.
Automated validation can then identify duplicate properties, normalize brand names, standardize addresses, geocode locations, and flag changes between collection periods. This is particularly important in a fast-moving development market where project status can change from proposed to construction, construction to opening, or planned to delayed.
Supply, Demand and Opportunity Monitoring
Dallas hotel chain supply and demand monitoring connects future room additions with market demand indicators. Developers can compare projected room supply against business travel, leisure activity, events, tourism, corporate expansion, airport traffic, and other demand drivers.
The approach can also identify potential oversupply. If multiple hotel projects cluster around the same corridor while demand indicators remain comparatively stable, investors may need to reconsider timing, brand positioning, or property scale.
Dallas hotel chain market opportunity forecasting takes the analysis one step further by combining historical development patterns with current pipeline activity. A forecasting model can score locations based on development momentum, competitive density, room growth, accessibility, nearby commercial development, and market demand.
This creates a forward-looking view of where hotel opportunities may strengthen or weaken.
Brand Footprint and Investment Strategy
Dallas hotel brand footprint analysis allows operators to compare their presence against competitors across the market.
A brand can identify neighborhoods with high competitor density but low internal penetration. Alternatively, it can identify markets where the brand already has several properties and determine whether additional expansion could create cannibalization.
This type of analysis is particularly useful when evaluating franchise territories, acquisitions, new construction opportunities, portfolio optimization, and market-entry strategies.
Dallas' development momentum is supported by broad economic and population growth. Industry reporting has repeatedly identified the region's business environment, tourism activity, and population expansion as contributors to its strong hotel pipeline.
Key Findings
Dallas leads the U.S. — Q2 2026 ended with 183 hotel projects and 22,840 rooms, the nation's largest pipeline.
Construction remains active — 38 Dallas projects totaling 4,184 rooms were under construction, also leading U.S. markets by project count.
Future supply is substantial — Dallas had 68 projects scheduled to begin construction within 12 months, creating a significant forward supply pipeline.
Planning activity remains high — Dallas led the country in early-stage projects, indicating continued de
